Car Insurance Online :: News
SHARE

Share this news item!

Harvest Fires Put Mallee Crop Losses in Sharp Relief

Fire-damaged crops raise questions about sums insured, evidence and continuity planning

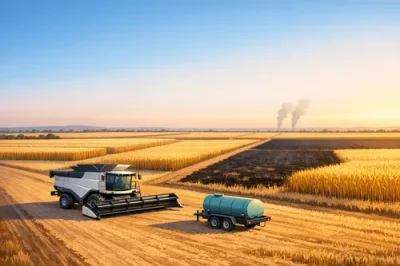
Harvest Fires Put Mallee Crop Losses in Sharp Relief?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Seven fires across Victoria’s north-west Mallee on Tuesday 10 November have turned harvest-season fire risk into an immediate business issue for grain growers.
ABC Rural reported on 11 November 2026 that the Country Fire Authority estimated about 300 hectares of crops were destroyed, including lentils near Walpeup and barley near Nandaly, with dry lightning and harvest activity among the triggers.

The timing matters. Crops close to harvest can represent months of input costs, seasonal risk and expected income sitting exposed in the paddock. A fire at that stage is not only a production loss; it can affect cash flow, grain contracts, machinery movements, labour plans and next season’s preparation. It also highlights how quickly a local incident can become a regional problem when multiple fires stretch emergency resources.

For insurance purposes, the key lesson is not simply that fire is a covered peril under many rural policies. The practical question is whether the relevant crop insurance section, declared crop values, acreage records, excesses, notification requirements and exclusions match the way the farm is actually operating at harvest. Farmers may also need to consider the boundary between standing crops, harvested grain, machinery, fencing, stored inputs and other property, because different policy sections can respond differently.

  • Keep paddock maps, crop type records and expected yield estimates up to date.
  • Record photos or drone footage before and after damage where it is safe to do so.
  • Document firefighting costs, contractor delays and clean-up work separately.
  • Check whether machinery, fencing, hay, fuel and stored grain sit under separate limits.

The CFA’s separate fire danger period updates this week also point to a wider seasonal issue: strong spring growth can create heavy fuel loads that dry quickly as warmer weather arrives. That makes natural disaster preparation more than a pre-summer checklist. Firebreaks, header maintenance, local communications, water access and neighbour response plans can all influence whether a small ignition remains manageable or spreads into a larger loss.

No policy can remove the frustration of losing a strong crop days before harvest, and insurance outcomes will depend on individual wording and evidence. However, these Mallee fires are a timely reminder that renewal conversations should include harvest-stage exposures, not just buildings and machinery. For mixed and broadacre farms, the most useful review is often the one that traces how value moves across the season: from growing crop, to harvested grain, to stored produce and then to sale.

Published:Thursday, 12th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

NHVR Prohibition Notice Puts Fleet Systems Under the Insurance Microscope
12 Nov 2026: Paige Estritori
A fresh National Heavy Vehicle Regulator action against a heavy vehicle operator is a timely reminder that insurance risk is not limited to what happens at the moment of a crash. The NHVR announced on 30 October 2026 that it had issued a prohibition notice after identifying significant and ongoing safety risks, including repeated defects in safety-critical systems and concerns about the operator’s management controls. - read more
Diagnosis timing is not the only test for income cover
12 Nov 2026: Paige Estritori
A recent income protection dispute has put fresh attention on a difficult but important issue for Australian workers: a medical condition may be treated as pre-existing even where a formal diagnosis comes later. The case, reported on 9 November 2026, involved a prostate cancer claim that was declined after the Australian Financial Complaints Authority accepted that earlier medical warning signs and specialist investigations were enough to trigger a pre-existing condition exclusion. - read more
Fuel Recovery Order Restarts, Raising Insurance Budget Questions
12 Nov 2026: Paige Estritori
The Fair Work Commission’s varied fuel cost recovery order will restart obligations from 23 November 2026, requiring covered road transport contractual chains to account for higher fuel costs against the 6 March 2026 benchmark. For truck operators, the immediate issue is contract pricing, but the insurance angle is also important: cash flow, route choices, subcontracting arrangements and vehicle utilisation all influence how risk is presented and managed. - read more
Court Ruling Highlights Why TPD Wording Matters for Business Owners
12 Nov 2026: Paige Estritori
A Queensland Court of Appeal decision involving AIA Australia has put renewed attention on how technical policy conditions can affect total and permanent disability claims, and why business owners should not treat insurance wording as a background detail. The case concerned group TPD cover held through superannuation, but its broader message is relevant to SMEs that rely on life, TPD and disability-style cover to protect debt, ownership arrangements and business continuity. - read more
Latest Claims Data Shows Why Policy Structure Still Matters
12 Nov 2026: Paige Estritori
APRA’s latest life insurance claims and disputes statistics, released on 16 October 2026 and covering the 12 months to 30 June 2026, provide a useful reminder for Australian businesses: the practical value of cover often depends on how clearly it is structured, documented and understood before a claim ever arises. - read more


Car Insurance Articles

Why Customisation Matters: Tailoring Car Insurance to Fit Your Needs
Car insurance customisation refers to the process of tailoring an insurance policy to fit the specific needs and circumstances of an individual driver or business. Unlike standard, one-size-fits-all policies, customised car insurance allows for the inclusion and exclusion of coverage options based on the unique requirements of the insured party. - read more
Comprehensive vs Third Party Car Insurance: Which Car Insurance Is Right for You?
Choosing car insurance in Australia is easier when you understand what each policy type is designed to cover. Comprehensive car insurance offers broader protection for your own vehicle and other people's property, while third party property cover is more limited and usually focuses on damage you cause to others. - read more
Car Insurance Savings: Tactics Aussies Can Use for Lowering Their Premiums
Car insurance is an essential aspect of vehicle ownership for Australians, providing financial protection in case of accidents, theft, and other unforeseen events. As with any form of insurance, the premiums you pay can vary widely, so understanding the factors that influence these costs is critical. - read more
How to Read a Car Insurance Policy Document in Australia
A car insurance quote is only a starting point. Before choosing or renewing cover, Australian drivers should read the policy documents carefully to understand inclusions, exclusions, excesses, conditions, cooling-off rights and claims obligations. - read more
Agreed Value and Market Value in Car Insurance Explained
Agreed value and market value affect how your car may be valued if it is written off or stolen. Understanding the difference can help Australian drivers compare comprehensive car insurance policies more carefully. - read more

Knowledgebase
Insurance Policy:
Broadly, the entire written contract of insurance. More narrowly, the basic written or printed document, as distinguished from the forms and endorsements added thereto.